Your Reputation Was Your Credit Score: The Vanished World of Trust-Based Business
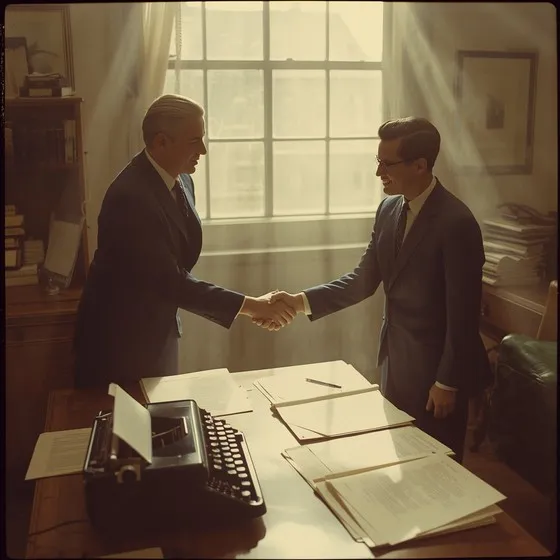
Photo: vintage handshake business deal men suit 1950s office, via images.stockcake.com
Somewhere around 1955, a hardware store owner in Dayton, Ohio extended a line of credit to a young contractor who'd just moved to town. No application form. No credit check — the concept barely existed in its modern form. No verification service, no digital identity confirmation, no algorithm running in the background.
What the hardware store owner had was a conversation. He'd asked around. He'd spoken to the contractor's former employer in Cincinnati, who vouched for him. He'd noted how the man carried himself, how he shook hands, whether he looked him in the eye. And then he made a judgment call — the same kind of judgment call that had governed American commerce for the better part of three centuries.
The contractor paid every invoice on time for forty years. The hardware store owner never lost a dime on him.
This is how trust used to work.
The Reputation Economy
Before the Fair Isaac Corporation introduced the FICO credit score in 1989 and before it became the dominant measure of financial trustworthiness in the 1990s, lending and business decisions operated on what you might call a reputation economy. Your standing in a community — what people said about you when you weren't in the room — was the primary currency of commercial life.
In small-town America, this system was almost self-enforcing. If you stiffed a supplier, word traveled fast and far. The local bank heard about it. The insurance agent heard about it. The next business that considered extending you credit heard about it. Your name, in a community where everyone knew everyone, carried the weight of your entire financial history — not as a number, but as a story that people passed along.
Even in larger cities, the mechanisms were surprisingly personal. Commercial banks had loan officers who made relationship-based decisions. If you'd been a customer for a decade, if the bank manager had watched you manage your account responsibly, that history counted for more than a formula. Chambers of commerce, trade associations, and civic organizations like the Rotary Club served partly as reputation clearinghouses — networks where businesspeople assessed each other's character before entering into agreements.
The handshake wasn't just a ritual. It was a binding act in a world where your word, once given in front of witnesses, was nearly impossible to walk back without social consequences that could follow you for years.
What Changed, and Why
The shift began gradually and then accelerated with technology. As American society became more mobile in the postwar decades — people moving between cities for work, businesses expanding beyond their regional roots — the old reputation networks started to fray. You couldn't ask around about someone who'd moved from Phoenix to Cleveland. The community context that made the system work began to dissolve.
Credit bureaus, which had existed in various forms since the late 1800s, expanded rapidly to fill the gap. By the 1970s, three major national credit reporting agencies were building standardized financial histories on millions of Americans. The FICO score formalized this into a single number that could travel anywhere, be accessed instantly, and theoretically reduce the complexity of a human life to something an underwriter in another state could act on in seconds.
The logic was sound: a scalable, objective system that could operate across a mobile, national economy. The personal relationship couldn't scale. The algorithm could.
And then the internet arrived, and the verification systems multiplied. Background check services. Identity verification platforms. Online review systems that quantified reputation into star ratings. LinkedIn profiles that encoded professional history into a searchable format. The informal, community-based assessment of character was replaced, layer by layer, with data.
What the Algorithm Misses
The modern system has genuine advantages that are easy to understate. FICO scores and credit reporting gave millions of Americans — particularly those who'd been excluded from relationship-based lending networks, including Black Americans who were systematically shut out of white-controlled financial institutions — a path to credit based on documented behavior rather than the subjective judgment of a banker who might not like the look of them. The objectivity of a number, for all its flaws, is more defensible than the subjectivity of a handshake.
But something real was lost in the translation.
The reputation economy captured things that algorithms can't. It assessed character under pressure — how someone behaved when things went wrong, whether they made good on a debt even when they technically could have walked away. It was forward-looking in a way credit scores aren't: a community could extend trust to a young person with no history because someone credible vouched for their potential. It accounted for context — the business that struggled during a drought, the contractor who fell behind on payments during a family crisis but had been solid for a decade before that.
A FICO score doesn't know any of that. It knows whether you paid the minimum balance on time.
There's also a behavioral dimension that the old system enforced and the new one doesn't. When your reputation was genuinely on the line — when burning a business partner meant facing them at the same church on Sunday morning — the social cost of bad behavior was immediate and personal. Today, disputes get routed through legal systems, dispute resolution services, and platform arbitration. The accountability is real, but it's abstract. It doesn't look you in the eye.
The Hybrid Future
Interestingly, some of the most successful modern platforms have tried to rebuild reputation-based trust on top of digital infrastructure. Airbnb's review system, eBay's seller ratings, and even LinkedIn's endorsements are all attempts to recreate, at scale, what the hardware store owner in Dayton did intuitively — aggregate the opinions of people who've dealt with someone and make that information available to the next party who needs to decide whether to trust them.
It's a reasonable approximation. But it's worth being honest about what it approximates. The star rating is a ghost of the handshake — a flattened, gameable, context-free shadow of the rich social information that a genuine community reputation carried.
The contractor in Dayton didn't have a profile. He had a name. And for most of American history, that was enough.